
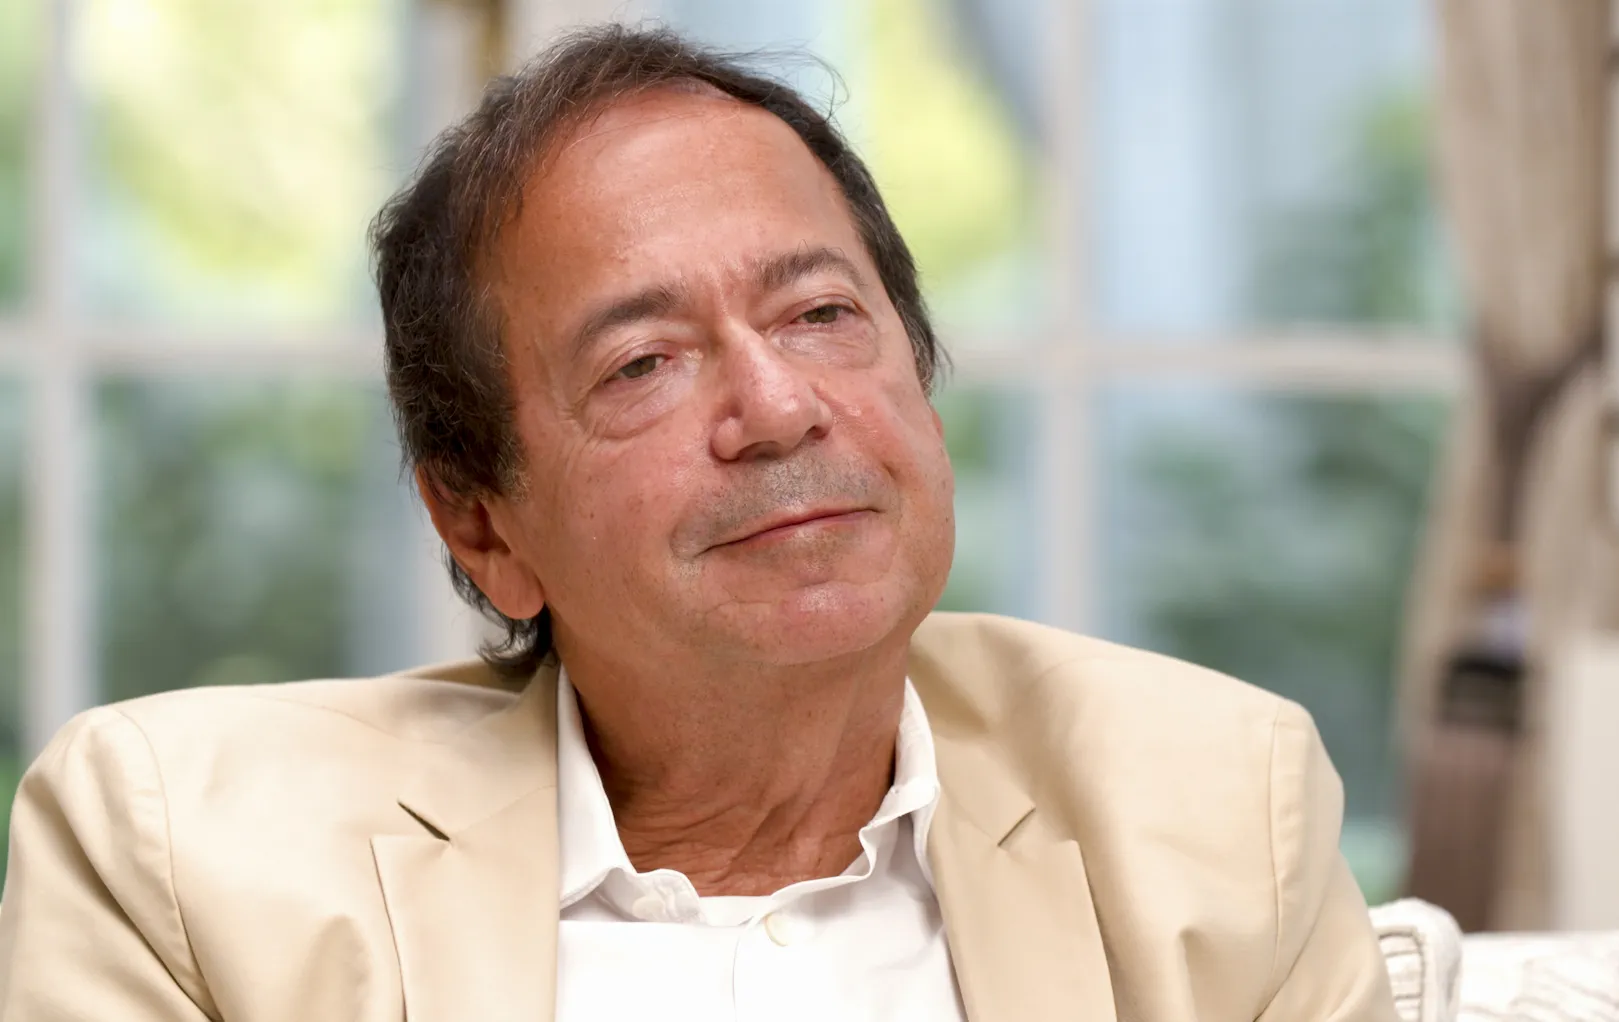
In the world of investing, some investors spend decades building successful careers, while a select few execute a single trade that completely transforms their lives and makes them famous around the world.
John Paulson belongs to the second category.
The American investor and founder of Paulson & Co. became internationally known for one of the most famous trades in financial history: betting against the U.S. housing market before the global financial crisis.
During the mid-2000s, the American housing market appeared to be experiencing an almost unstoppable boom. Home prices were rising, banks were issuing mortgages at an unprecedented pace, and investors were purchasing mortgage-backed securities as seemingly attractive financial assets.
But Paulson saw something different.
After studying the subprime mortgage market, he became convinced that the growth was unsustainable and that the financial system had become increasingly dependent on weak-quality loans and inflated asset valuations.
Instead of joining investors who were betting that the housing boom would continue, Paulson decided to position his funds for a collapse.
The result became one of the most profitable investment trades in modern financial history.
In 2007, his funds generated enormous profits from the strategy, while Paulson personally earned approximately $4 billion that year.
But John Paulson’s story did not begin with the financial crisis.
Before becoming famous, he spent years developing his investment expertise, building a relatively small hedge fund, and competing in an industry where his name was largely unknown outside professional investment circles.
Early Life
John Alfred Paulson was born on December 14, 1955, in New York City.
He grew up in Queens and developed an early interest in business and investing.
Paulson did not inherit a massive financial empire. Instead, he gradually built his professional career through education and experience in the financial industry.
Over time, he developed a particular interest in deals, acquisitions, corporate restructuring, and valuation.
These areas would eventually become important elements of his investment strategy.
Education
Paulson attended New York University, where he earned his undergraduate degree.
He later attended Harvard Business School, earning a Master of Business Administration.
His education gave him a strong foundation in finance, strategy, and business analysis.
However, much of his most important investment knowledge came later through years of practical experience on Wall Street.
Starting His Career on Wall Street
After completing his education, Paulson worked at several financial and investment firms.
Among the organizations he worked for were Boston Consulting Group and Bear Stearns, where he gained experience in financial analysis, mergers and acquisitions, corporate restructuring, and risk assessment.
These experiences helped shape his investment approach.
Paulson was not simply interested in tracking market prices. He preferred to study the underlying structure of transactions, the value of assets, and risks that might not be obvious from headline financial figures.
Founding Paulson & Co.
In 1994, John Paulson founded his own investment firm, Paulson & Co., in New York.
Compared with the largest hedge funds on Wall Street, the company began relatively small.
Its early strategies included merger arbitrage, special situations, and event-driven investments.
The basic idea was to identify situations where the market price of an asset differed significantly from what Paulson believed its underlying value would eventually become.
Years Away from the Spotlight
Before 2007, John Paulson was not a household name.
Paulson & Co. operated as a specialized hedge fund while Paulson continued developing his expertise in analyzing complex transactions and managing investment risk.
The firm was successful, but it had not yet produced the extraordinary results that would later make it one of the most famous investment firms in the world.
Paulson needed a major investment opportunity that could fundamentally change the scale and reputation of his business.
That opportunity emerged when he began studying the American housing market.
Becoming Skeptical of the Housing Market
As U.S. home prices continued rising, Paulson began examining the mortgages behind the boom.
He noticed that an increasing amount of lending was going to borrowers with weak credit profiles, commonly known as subprime borrowers.
He also observed that banks and financial institutions were packaging these mortgages into increasingly complex securities and selling them to investors as relatively attractive financial instruments.
Paulson identified a fundamental vulnerability.
If home prices stopped rising, large numbers of borrowers could struggle to repay their mortgages.
That could cause the value of mortgage-backed securities to collapse, potentially creating losses far beyond the housing sector itself.
Seeing What the Market Missed
By 2006, Paulson had become convinced that the subprime mortgage market was heading toward a major collapse.
Instead of buying real estate assets like many investors, he began searching for a financial instrument that could generate profits if mortgage-related assets declined in value.
He found the answer in Credit Default Swaps (CDS).
These contracts could be used to hedge against credit risk or take positions that benefited from the deterioration of certain debt instruments.
Paulson began building large positions tied to subprime mortgage-backed securities.
The strategy involved significant risk.
If the housing market continued rising, his funds could lose substantial amounts of money while maintaining those positions.
But Paulson believed the probability of a major collapse was far greater than the market recognized.
The Bet That Changed His Life
In 2007, the subprime mortgage market began collapsing.
As mortgage defaults increased, the value of securities linked to those loans started falling.
The problems quickly spread beyond housing and into the broader financial system, eventually contributing to the global financial crisis that reached its peak in 2008.
For John Paulson, however, the economic disaster became one of the most profitable trades in investment history.
His funds generated extraordinary returns from the strategy, while Paulson personally earned approximately $4 billion in 2007.
The achievement transformed him from a relatively obscure hedge fund manager into one of the world’s most famous investors.
Executing the Bet That Changed John Paulson’s Career
John Paulson’s success during the financial crisis was not simply the result of luck or a random investment decision.
Behind the trade that later became one of the most famous transactions in Wall Street history were years of research, analysis, and an effort to understand how the U.S. mortgage market actually worked.
Paulson believed the problem was not simply that home prices had become too high. He believed an entire financial system had developed around those prices, creating risks that investors were seriously underestimating.
Studying the Mortgage Market
Paulson & Co. began analyzing large amounts of mortgage data, paying particular attention to subprime loans.
The team discovered that many borrowers had received mortgages under terms that did not necessarily match their ability to repay.
Some loans also offered unusually low initial interest rates that could rise substantially later, potentially pushing monthly payments beyond what borrowers could afford.
For Paulson, the key question was simple: What would happen if home prices stopped rising?
If prices declined, many homeowners would struggle to refinance or sell their properties at sufficient prices to cover their mortgages.
Mortgage defaults could then increase rapidly.
Using Credit Default Swaps
Paulson needed an instrument that could allow his funds to profit if mortgage-backed securities deteriorated.
That instrument was the Credit Default Swap, commonly known as a CDS.
In simple terms, these contracts could provide protection against the failure or deterioration of certain debt instruments.
Paulson’s funds would pay a recurring premium for this protection.
If the underlying securities continued performing well, the cost of maintaining those positions would continue.
But if the securities suffered severe losses, the value of the protection could increase dramatically.
Betting Against the Market
Paulson began building large positions against subprime mortgage-backed securities.
His strategy was almost completely contrary to the prevailing market sentiment.
At the time, many investors viewed mortgage-related securities as relatively safe investments.
Credit rating agencies had also assigned high ratings to many of these products, reinforcing investor confidence.
Paulson, however, believed those ratings failed to reflect the true risks embedded in the underlying mortgages.
Bringing in Specialists
Paulson did not rely solely on his own intuition.
Paulson & Co. worked with specialists who analyzed mortgage data and examined how different groups of loans might perform if housing prices declined.
The objective was to identify securities with the greatest exposure to deteriorating mortgage quality and then build positions that could benefit from their decline.
This required extensive analysis rather than simply predicting that housing prices would eventually fall.
The Turning Point in 2007
Paulson’s thesis began to play out in 2007.
Defaults on subprime mortgages increased, and the value of mortgage-backed securities began falling.
It soon became clear that the problem was much larger than a conventional housing downturn.
Banks and financial institutions around the world held significant exposure to mortgage-related instruments.
As losses accumulated, the crisis spread from the housing market into the broader financial system.
Extraordinary Profits
While major financial institutions were suffering enormous losses, Paulson’s funds generated extraordinary returns.
One of his funds, which had been positioned specifically to benefit from the collapse of subprime mortgages, produced exceptional gains.
The results turned Paulson into one of the most successful hedge fund managers in the world.
In 2007 alone, he personally earned approximately $4 billion, an extraordinary figure that permanently connected his name with the financial crisis.
Was It Just Luck?
After the crisis, some observers argued that Paulson’s success was primarily the result of extraordinary timing rather than a strategy that could easily be repeated.
But there was an important distinction.
Paulson did not establish his positions immediately before the collapse.
He spent considerable time building them before the crisis became obvious to the wider market.
During that period, he had to continue paying the cost of maintaining his positions while the housing market was still rising.
If his thesis had been wrong, those expenses could have resulted in substantial losses.
Psychological and Financial Pressure
The strategy was expensive to maintain.
Paulson’s funds had to continue paying premiums on their credit protection while the market initially moved against them.
As housing prices continued rising, the positions could easily have appeared to be a mistake.
But Paulson remained committed to his analysis.
He believed the underlying data did not support the market’s confidence in the housing sector.
His ability to tolerate short-term pressure while maintaining a long-term investment thesis became an important part of the trade’s eventual success.
The Global Financial Crisis
By 2008, the crisis had reached a much more dangerous stage.
Major financial institutions began failing or requiring emergency assistance, stock markets plunged, and credit markets became severely disrupted.
The collapse of Lehman Brothers in September 2008 became one of the defining moments of the crisis.
What had started as a problem in the U.S. housing market had become a global financial emergency.
For Paulson, however, the crisis represented the culmination of a thesis he had been developing for years.
From Specialized Investor to Global Celebrity
Before the crisis, John Paulson was primarily known within the specialized world of hedge funds.
Afterward, his name became internationally recognized.
He became the investor who had identified the weaknesses in the mortgage market before the collapse and positioned his funds accordingly.
His story became the subject of books, documentaries, financial analysis, and countless discussions about how investors can identify systemic risks before they become obvious.
But his newfound fame created a new challenge:
Could John Paulson continue generating extraordinary returns after the market event that made him famous had already passed?
Life After the Financial Crisis
After becoming one of the world’s most famous investors, John Paulson entered a completely different phase of his career.
The challenge was no longer proving that he could generate extraordinary returns.
It was finding new opportunities in markets that were fundamentally different from the environment that had produced his historic 2007 gains.
New Investment Opportunities
Following the financial crisis, Paulson & Co. expanded its investments across a broader range of industries and strategies.
Paulson focused on opportunities involving:
- Financial companies.
- Real estate.
- Gold and precious metals.
- Healthcare.
- Technology.
- Restructuring situations.
- Mergers and acquisitions.
His strategy remained centered on identifying situations where he believed the market price did not accurately reflect an asset’s underlying value or future potential.
Investing in Gold
Gold became one of Paulson’s most notable areas of interest after the financial crisis.
Concerns about inflation, monetary policy, and massive government stimulus led him to believe that gold could provide protection against certain economic risks.
He invested in gold-related companies and mining projects and became one of the most prominent hedge fund managers associated with a bullish view on the precious metal.
However, some of these investments did not perform as successfully as his historic mortgage trade.
Healthcare Investments
Paulson also became active in the healthcare sector.
He focused on companies that he believed had strong growth potential or could benefit from mergers, acquisitions, or other corporate events.
This approach reflected his broader investment philosophy.
Rather than simply predicting whether a stock would rise or fall, Paulson often looked for specific events that could change the market’s valuation of a company.
Not Every Investment Worked
John Paulson’s post-crisis career also demonstrated an important reality of investing: even highly successful investors make significant mistakes.
Several investments made after 2008 suffered substantial losses.
This highlighted the difference between executing one of the most successful trades in financial history and consistently producing extraordinary returns across different market environments.
Paulson & Co. faced the challenge of rebuilding its investment performance after the opportunity that had created its global reputation had disappeared.
Moving Toward a Family Office
Over time, Paulson & Co. changed its business model.
The firm increasingly focused on managing John Paulson’s own wealth and family capital rather than operating solely as a traditional hedge fund for outside investors.
In 2020, the firm announced that it would transition toward a family office structure.
The move allowed Paulson to focus more heavily on his own investments and long-term wealth management without the same pressures associated with managing a large traditional hedge fund.
John Paulson’s Net Worth
Following his extraordinary profits during the financial crisis, John Paulson became a billionaire.
Much of his wealth has remained invested across a wide range of assets, including financial investments, real estate, precious metals, and other private holdings.
His net worth has fluctuated over time as asset values and market conditions changed, but he has remained one of America’s wealthiest investment managers.
His historic mortgage trade remains the event most closely associated with the creation of his fortune and global reputation.
Philanthropy
John Paulson has also directed a significant portion of his wealth toward philanthropy.
He has donated hundreds of millions of dollars to educational, healthcare, cultural, and scientific institutions.
One of his most notable philanthropic commitments has been to New York University, where his contributions have supported education and academic programs.
He has also supported medical institutions, cultural organizations, and community initiatives.
Paulson’s Investment Philosophy
John Paulson’s investment philosophy centers on identifying the gap between an asset’s fundamental value and its market price.
He does not focus exclusively on what is happening today.
Instead, he tries to understand what could happen if the underlying conditions change.
Several principles stand out from his career:
- Do not blindly follow market consensus.
- Search for risks that other investors overlook.
- Understand the underlying assets in detail.
- Be willing to withstand short-term pressure when the analysis remains strong.
- Never assume past success guarantees future performance.
- Treat risk management as seriously as return generation.
Lessons from John Paulson’s Journey
Paulson’s career offers several important lessons for investors and entrepreneurs.
First, extraordinary opportunities can emerge when an investor identifies a problem that most of the market has failed to recognize.
Second, taking a position against the majority can generate exceptional returns, but only when supported by rigorous research and the ability to withstand temporary losses.
Third, timing matters, but preparation before the event is often even more important.
Fourth, even the greatest investors make mistakes, and no strategy works in every economic cycle.
Finally, preserving wealth after creating it requires risk management and discipline just as much as the skills that created the original fortune.
Major Achievements
John Paulson’s most significant accomplishments include:
- Founding Paulson & Co. in 1994.
- Identifying the risks in the U.S. subprime mortgage market before the global financial crisis.
- Generating extraordinary profits by betting against mortgage-backed securities.
- Personally earning approximately $4 billion in 2007.
- Building a multi-billion-dollar personal fortune through investment management.
- Donating substantial amounts to educational, healthcare, scientific, and cultural institutions.
- Transitioning Paulson & Co. toward a family-office model focused on long-term private wealth management.
Legacy
John Paulson’s legacy is not based solely on the fortune he accumulated.
His most important contribution to investment history may be the mortgage trade that demonstrated how deeply flawed assumptions within financial markets can create enormous opportunities for investors willing to challenge consensus.
His story also reveals another important lesson.
Even an investor who executes one of the most profitable trades in history cannot depend on past success forever.
Markets change, opportunities disappear, and strategies must evolve.
Final Thoughts
John Paulson’s story is one of the most fascinating investment journeys of the modern era.
From a relatively unknown hedge fund manager, he became one of the world’s most famous investors by studying the U.S. mortgage market and positioning his funds for a collapse that few investors anticipated.
But the most important lesson from his career is not simply the billions he earned.
It is the importance of independent thinking, detailed analysis, risk management, and the willingness to challenge prevailing assumptions when the evidence supports a different conclusion.
John Paulson’s journey demonstrates that successful investing is not always about predicting exactly what will happen.
It is about identifying risks others overlook, preparing for different outcomes, and building a strategy capable of benefiting when the market eventually recognizes what you saw first.